Built from the other side
of the credit table.
AWG exists because entrepreneurs should have access to sophisticated credit judgment before they make a major capital decision.
 Our origin
The judgment arrived too late.
AWG started with something we saw too often.
Good entrepreneurs were making some of the biggest financial decisions of their lives without anyone on their side who had ever been responsible for approving one.
Goran Pavlovski has worked in banking and credit since 2017. He saw good businesses financed well. He saw good businesses financed badly. And he saw good transactions fall apart because of decisions made months before the file ever reached credit.
 From the founder
Nearly a decade on the side that had to say yes or no.
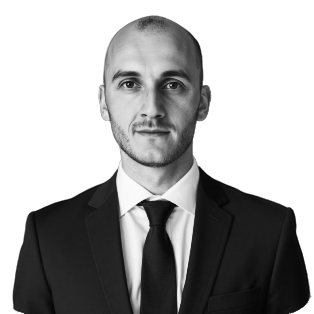
Before founding AWG, Goran built his career in commercial and SBA banking and credit. His job was not to sell the loan. It was to decide whether the bank should make it.
Those years were spent understanding how businesses generate cash, why transactions fail, what makes a structure resilient, and what makes an approval difficult long before anyone calls it difficult.
Today, Goran also advises and trains SBA lending teams on credit analysis, underwriting discipline, and the practical application of SBA policy, helping them make better-supported credit decisions.
That work keeps his perspective current and reinforces the conviction behind AWG: entrepreneurs should have access to that judgment before the bank does. AWG was founded to put it on their side of the table.
Deals reviewed
SBA loans approved and closed
Former individual SBA credit approver in the U.S. · 2023
How we thinkBefore a lender sees your file.
We ask the questions that shape whether the financing should happen—and how.
 Credit review
What this means for you
Can the business carry the debt?
Cash flow · Working capital · Debt structureJudgment before placement.
We assess the business, transaction and financing structure before approaching lenders, so the credit risks are understood early.
What could stop the transaction?
Price · SBA eligibility · Downside riskSay what we see.
If the price, structure or cash flow does not support the debt, we say so. We explain what would need to change—and when the right answer is not to proceed.
What remains open through closing?
Lender questions · Conditions · ExecutionStay involved through closing.
The person who understands your transaction stays involved through structuring, lender selection, underwriting and closing—especially when difficult questions arise.
TestimonialsWhat partners say
“If a deal doesn’t look good, he’ll tell the buyer right away, even though he only gets paid when the deal closes. That kind of integrity is rare, and it’s why I trust working with him.”
“AWG is clearly more than a loan brokerage. It is a true advisory, helping clients structure their deals and working with them closely to ensure that they obtain the necessary financing.”
“Many banks turned us away… Not only has he found a bank to work with but he maintained excellent communication throughout the process.”
Our processFrom first review to closing.
Assess
We review your financials, business operations and financing needs.
Pressure-test
We test repayment capacity, SBA eligibility and credit risks.
Optimize
We refine the structure, match suitable lenders and prepare the credit memo.
Execute
We help you evaluate lender terms and guide you through approval and closing.